Hunting PLC – Annual report – 31 December 2025
Industry: oil and gas
41. Material accounting policies (extract)
(b) Revenue
(i) Revenue from contracts with customers
- Revenue is recognised as performance obligations are satisfied when control of promised goods or services is transferred to the customer and is measured at the amount that reflects the consideration to which the Group expects to be entitled in exchange for those goods or services.
- •For each performance obligation within a contract, the Group determines whether it recognises revenue:
1. Wholly at a single point in time when the Group has completed its performance obligation; or
2. Piecemeal over time during the period that control incrementally transfers to the customer while the goods are being manufactured or the service is being performed.
- Hunting’s activities that require revenue recognition over time comprise:
1. The supply of goods that are specifically designed for, and restricted to, the use of a particular customer, and for which Hunting has an enforceable right to payment for the work completed to date, for example, the design and manufacture of bespoke products such as titanium stress joints;
2. The provision of services in which Hunting creates or enhances an asset that the customer controls as the asset is created or enhanced, such as the lathing of a thread onto the ends of customer-owned plain-end pipe and assembling or welding components that are owned by the customer; and
3. The provision of services in which the customer obtains the benefit while the service is being performed, such as the storage and management services of customer-owned products.
- In respect of revenue that is recognised over time, Hunting uses an input method for measuring the progress towards completion of its performance obligations and consequently for measuring the amount of revenue that is recognised. Specifically, revenue is recognised in proportion to the total expected consideration that mirrors the costs incurred to date relative to the total expected costs to complete the performance obligation. This method is considered to be the most appropriate as the inclusion of all costs, being materials, labour and direct overheads, best reflects the activities required in performing the promise to the customer.
- Hunting’s activities that require revenue recognition at a point in time comprise:
1. The sale of goods that are not specifically designed for use by one particular customer. These products include tubulars acquired by Hunting as plain-end pipe on which lathing work has been applied and which are resold as threaded pipe; and
2. The manufacture of goods that are specifically designed for one particular customer but for which Hunting does not have an enforceable right to payment for the work completed to date.
- In determining the point in time in which control is transferred to customers and revenue is recognised, the Group evaluates all relevant facts and circumstances.
- The events that trigger the recognition of revenue at a point in time are most commonly: (i) delivery of the product in accordance with the contractual terms, or (ii) when confirming shipping documents, which indicate transfer of legal title and an ability to direct the goods, are made available to a customer, before which the Group retains the ability to direct the use of, and obtain, substantially all of the remaining benefits from the goods, or (iii) when the product is made available to the customer for collection.
- When revenue from a customer is recognised, the amount is reported on the balance sheet as a contract asset if the performance obligation is incomplete as this asset reflects that it is conditional upon Hunting completing the work. The revenue is recognised on the balance sheet as a trade receivable if a sales invoice has been issued as this asset reflects that it is unconditional other than the passage of time. The revenue is reported on the balance sheet as accrued income if the performance obligation has been completed but a sales invoice has not yet been issued. Accrued income is a sub-category of trade receivables, where receipt of cash is dependent only upon the passage of time. The Group recognises a contract liability on the balance sheet when amounts received and receivable from the customer exceed the value of the work done to date, reflecting that the Group is obligated to transfer goods or services in order to settle the prepayment from the customer.
(ii) Rental revenue
- Rental revenue from operating leases, being leases in which Hunting does not transfer substantially all of the risks and rewards of the leased asset to the customer, is recognised as the income is earned. For Hunting this comprises the leases of properties to third parties and tools to customers.
- Revenue from finance leases, being leases in which Hunting, as a manufacturer/dealer-lessor, transfers substantially all of the risks and rewards of the leased asset to the customer, is measured as the fair value of the underlying asset or, if lower, the present value of the lease payments. The carrying value of the leased asset minus the unguaranteed residual value is charged to cost of sales and interest earned during the term of the lease is recognised as finance income.
1. Basis of preparation (extract)
Critical accounting judgements and key sources of estimation uncertainty (extract)
Critical accounting judgements are those that the Directors have made in the process of applying the Group’s accounting policies and that have the most significant effect on the amounts recognised in the Group’s financial statements. Key estimates are those concerning future expectations and other key sources of estimation uncertainty at the end of the reporting period and which may have a significant risk of causing a material adjustment to the carrying amounts of assets and liabilities within the next financial year. Critical accounting judgements were made in the following areas:
- In determining the point in time at which control is transferred to customers and revenue is recognised, as described in note 41(b). In the majority of Hunting’s contracts this is straightforward. However, the determination can become more complex in contracts where goods are shipped and confirming shipping documentation, indicating transfer of legal title and an ability to direct the goods, can take a short period of time to be produced and provided to the customer, which can be after the ship has departed port and the transfer of risk has occurred. In applying the Group’s revenue recognition policy, in these instances, the Group’s judgement is to recognise revenue at the point in time when the confirming shipping documentation is provided to the customer which could potentially be in a different accounting period to when the goods are loaded onto the ship and risk transfers, in accordance with incoterms. At 31 December 2024, there was a shipment at sea containing goods with a revenue value of c.$32m. Risk had transferred to the customer per the stated incoterms; however, the confirming shipping documentation had not been produced and, therefore, the Group still had the ability to direct the goods. Management considered the different indicators of control in accordance with IFRS 15 and concluded that Hunting retained control of the goods at 31 December 2024 and, therefore, revenue was recognised in 2025;
- In determining if the contractual terms for various significant customer contracts met the requirements for over time revenue recognition, as described in note 41(b);
3. Revenue
In the following tables, a breakdown of the Group’s different revenue streams by segment has been given, including the disaggregation of revenue from contracts with customers.
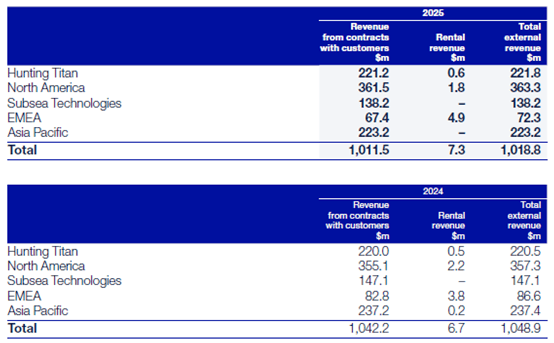
Revenue is typically recognised for products when the product is shipped or made available to customers for collection, or over time as control of the product is transferred to customers, and for services either on completion of the service or, at a minimum, monthly for services covering more than one month. Rental revenue is earned from the rental of tools, see note 24(d).
Of the revenue from contracts with customers, $723.9m (restated 2024 – $799.4m) was recognised at a point in time and $287.6m (restated 2024 – $242.8m) was recognised over time. The Group’s revenue recognised over time is predominantly within the North America and Subsea Technologies operating segments.
The amount of consideration is not adjusted for the effects of a significant financing component as, at contract inception, the period between when the entity transfers a promised good or service to a customer and when the customer pays for that good or service will be one year or less.
18. Trade, contract and other receivables
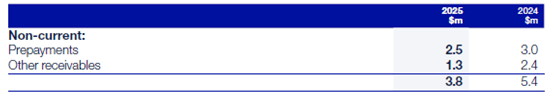
Other receivables includes finance lease receivables of $1.2m (2024 – $2.3m), see note 24 for further details.
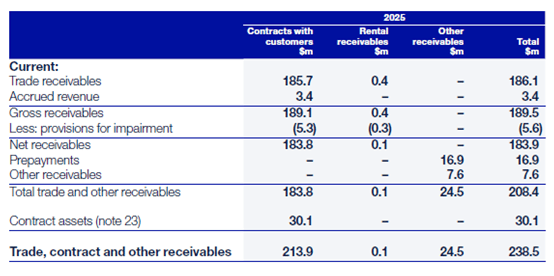
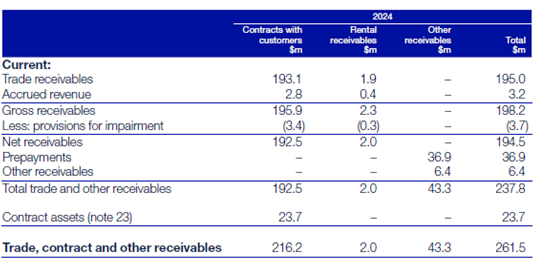
Current and non-current other receivables generally arise from transactions outside the usual operating activities of the Group and comprise receivables from tax (VAT, GST, franchise taxes, and sales and use taxes) of $3.0m (2024 – $3.5m), derivative financial assets of $0.1m (2024 – $0.5m), finance lease receivables of $2.0m (2024 – $2.6m) (note 24) and other receivables of $3.8m (2024 – $2.2m). Finance lease receivables and other receivables are classified as financial assets measured at amortised cost.
During the year, the Group sold trade receivables amounting to $69.2m (2024 – $59.2m) to third parties under trade receivables purchasing programmes in order to accelerate collections. Upon sale, the receivables were derecognised from the balance sheet.
Impairment of trade, contract and other receivables
The Group applies lifetime expected credit losses (“ECLs”) to trade receivables, accrued revenue, contract assets and certain other receivables upon their initial recognition. Each entity within the Group uses provision matrices for recognising ECLs on its receivables, which are based on actual credit loss experience over the past two years, as a minimum. Receivables are appropriately grouped by geographical region, product type or type of customer, and separate calculations produced, if historical or forecast credit loss experience shows significantly different loss patterns for different customer segments. Actual credit loss experience is then adjusted to reflect differences in economic conditions over the period the historical data was collected, current economic conditions, forward-looking information based on macroeconomic information and the Group’s view of economic conditions over the expected lives of the receivables. The contract assets relate to unbilled work in progress and have substantially the same risk characteristics as the trade receivables and accrued revenue for the same types of contracts. It has therefore been concluded that the expected loss rates for trade receivables are a reasonable approximation of the loss rates for the contract assets.
At 31 December 2025, the ageing of the Group’s gross financial assets, based on days overdue, is as follows:
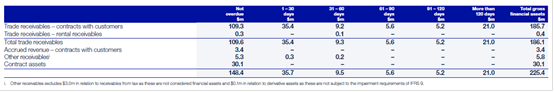
Since 31 December 2024, there has been an increase in the ageing of trade receivables with trade receivables not overdue at the year-end comprising 59% of gross trade receivables compared to 62% at 31 December 2024. Overdue debts arise due to a number of different factors, including the time taken in resolving any disputes, a culture of slow/late payment in some jurisdictions and some debtors experiencing cash flow difficulties.
At 31 December 2024, the ageing of the Group’s gross financial assets, based on days overdue, is as follows:
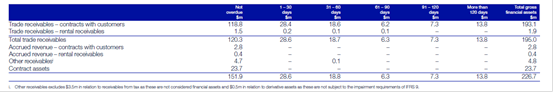
Concentrations of credit risk with respect to trade receivables are limited due to the Group’s wide and unrelated customer base. The maximum exposure to credit risk is the carrying amount of each class of financial asset disclosed above. The carrying value of each class of receivable approximates their fair value as described in note 29(b)(iv).
Default on a financial asset is usually considered to have occurred when any contractual payments under the terms of the debt are more than 90 days overdue. Usually, no further deliveries are made or services provided to customers that are more than 90 days overdue unless there is a valid reason to do so, such as billing issues that have prevented the customer from settling the invoice. Permission from the local financial controller can be obtained to continue trading with customers with debts that are more than 90 days overdue, and the outstanding debts may also be rescheduled with the permission of the financial controller.
While a proportion, 14% (2024 – 11%), of the Group’s trade receivables are more than 90 days overdue, the majority of these have not been impaired. Some of these debts have become overdue due to billing and other issues or due to general slow payment by the customer. Where there is no history of bad debts and there are no indicators that the debts will not be settled, the receivables have not been impaired. These customers are monitored very closely for any indicators of impairment.
Receivables are written off when there is no reasonable expectation of recovery. Indicators that receivables are generally not recoverable include the failure of the debtor to engage in a repayment plan, failure to make contractual payments for a period greater than 180 days past due and the debtor being placed in administration. Where receivables have been written off, the Group will continue to try to recover the outstanding receivable. Impairment losses on receivables are presented net of unused provisions released to the consolidated income statement within administrative expenses. Subsequent recoveries of amounts previously written off are credited against the same line item.
Credit risk arises on accrued revenue where goods or services have been provided to a customer but the amount is yet to be invoiced. The accrued revenue balance is short term and relates to customers with a strong credit history. Therefore, the ECLs on this balance are immaterial and no provision for impairment has been recognised.
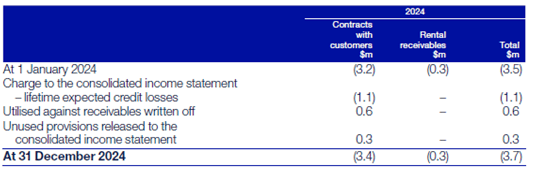
During the year, the movements on the provisions for impairment were as follows:
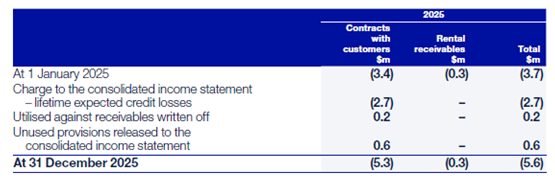
The provision for the impairment of trade and other receivables has increased by $1.9m to $5.6m at 31 December 2025. However, management is of the view that the credit risk is largely unchanged during the year as the increase is due to a one-off instance with a specific customer.
22. Trade, contract and other payables
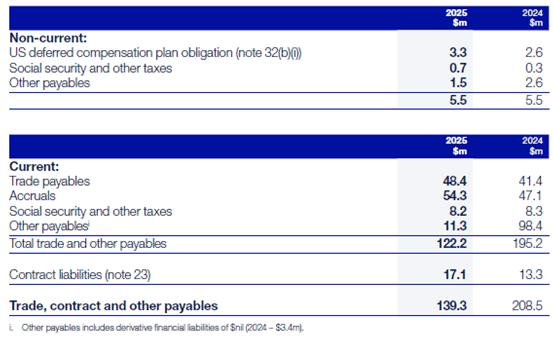
Within other payables in 2025 is a financial liability for $6.5m in relation to an obligation for Hunting to purchase its own shares (note 33) and contingent consideration of $0.8m arising on the acquisition of FES (note 40).
Within other payables in 2024 are amounts totalling $92.4m in relation to payments due to financial institutions arising under bank acceptance drafts, which represent payments to suppliers for materials.
23. Contract assets and liabilities
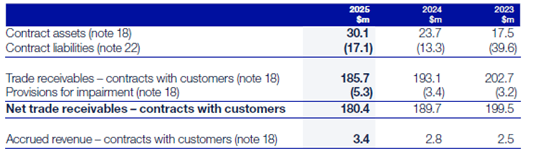
The following table provides information about receivables, accrued income, contract assets and contract liabilities arising from contracts with customers.
(a) Significant changes in contract assets and contract liabilities
Contract assets increased from $23.7m at 31 December 2024 to $30.1m at 31 December 2025 due to an increase in bespoke customer work-in-progress at Subsea Technologies invoiced in arrears, mainly resulting from the acquisition of FES, see note 40.
Contract liabilities represent deposits received from customers (or amounts presently due under non-cancellable contracts) in excess of the value of the work completed to date at Subsea Technologies, as well as deposits received from customers for the purchase of goods in other business units.
(b) Revenue recognised in relation to contract liabilities
During the year, $13.3m of revenue was recognised in relation to amounts that were included in the contract liabilities balance at the beginning of the year (2024 – $39.6 m). There was no revenue recognised from performance obligations satisfied or partially satisfied in previous years (2024 – none).
(c) Unsatisfied performance obligations
The Group applies the practical expedient in paragraph 121 of IFRS 15 and does not disclose information about remaining performance obligations that are part of contracts that have original expected durations of one year or less. This is the vast majority of Hunting’s contracts with customers.
For the contracts that have original expected durations of greater than one year, the aggregate amount of the transaction price allocated to partially or fully unsatisfied performance obligations as at the year-end is $105.1m (2024 – $203.7m). It is expected that $23.1m of the transaction price allocated to unsatisfied performance obligations as of 31 December 2025 will be recognised as revenue in 2026 (2024 – $184.5m in 2025) and the remaining $82.0m in future years (2024 – $19.2m after 2025).

