Sasol Limited – Annual report – 30 June 2026
Industry: oil and gas
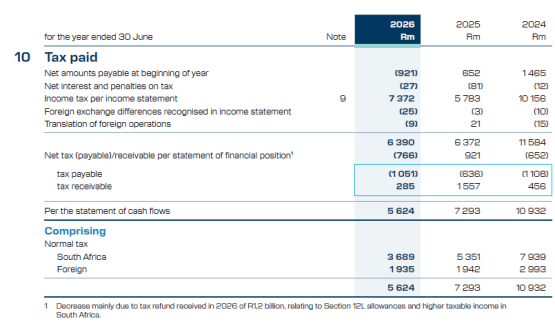
9 Taxation (extract)
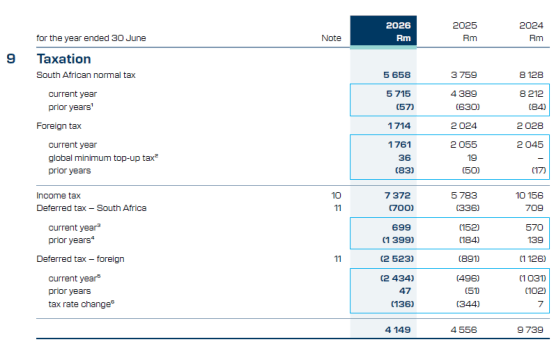
1 Relates to Section 12L (South African income tax incentive for energy-efficiency) allowances refer footnote 4.
2 In respect of Pillar Two that introduced a 15% global minimum effective tax rate for large multi-national entities. The Group has applied a temporary mandatory relief from deferred tax accounting for the impacts of the top-up tax and accounts for it as a current tax.
3 Mainly due to the assessed loss utilised in Sasol South Africa Limited (SSA) in 2026.
4 Mainly attributable to the R850 million prior year Section 12L energy efficiency allowance claim, which increased the assessed loss and consequently the deferred tax asset recognised.
5 The increase relates mainly to tax losses in the US, unwinding of deferred tax liability on Mozambique assets and current year impairments.
6 2026 mainly relates to the effect of future tax rate change in Germany on the realisation of deferred tax balance. 2025 relates mainly to Louisiana (US) tax rate reduction that was enacted.
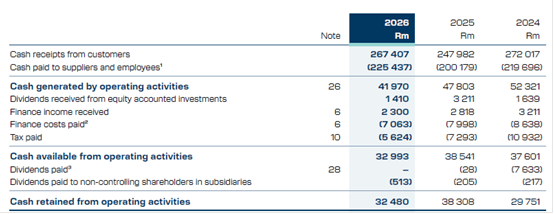
STATEMENT OF CASH FLOWS (extract)
for the year ended 30 June
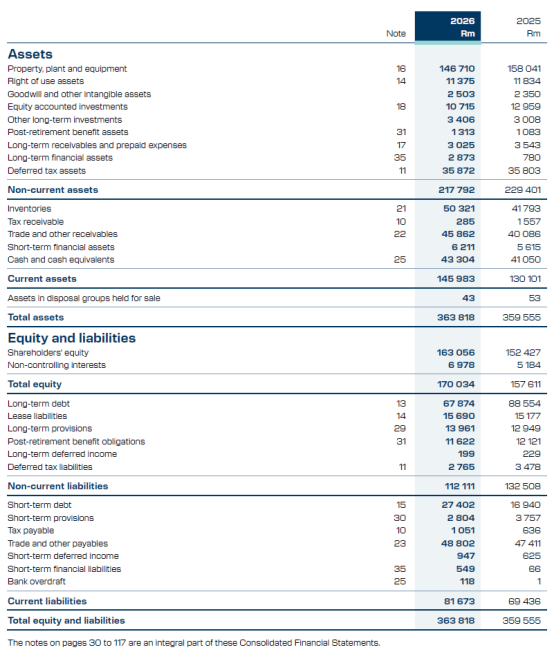
STATEMENT OF FINANCIAL POSITION
at 30 June
 Accounts examples
